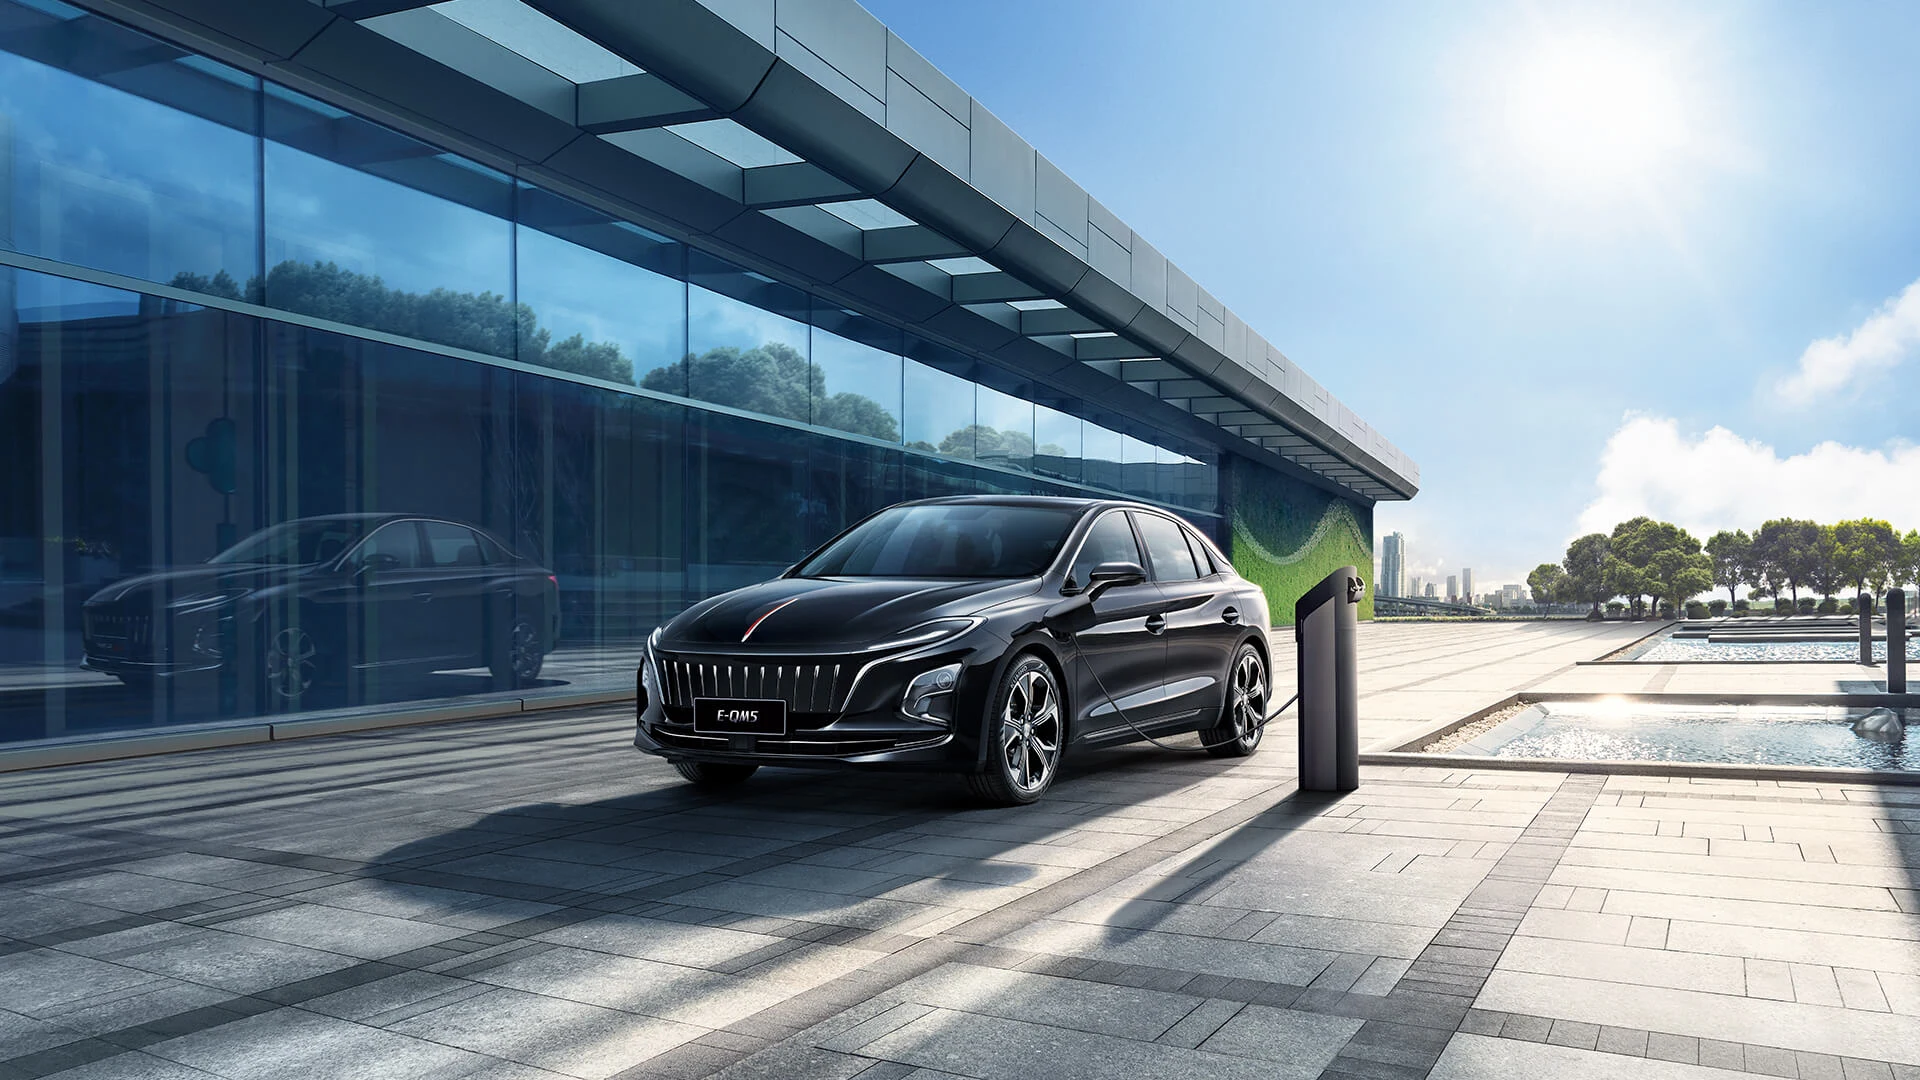
Fix the use and accounting boundary
Identify whether the worksheet concerns dealer stock, a private user or a working vehicle. Set the three-year period, annual distance and which expenses are counted. A dealership’s holding and resale model is different from three years of customer driving, so do not blend the two without explanation. The acquisition worksheet provides the starting cost boundary. State currency and dates for actual inputs. Decide whether finance and the value of time are included; if they are omitted, say so rather than allowing the word total to imply a comprehensive calculation that the chosen scope does not support.
Start with a genuinely ready acquisition amount
Include the accepted vehicle and battery, supported preparation, relevant equipment and the actual delivery and local readiness costs in scope. Obtain current quotations from the responsible providers. If a necessary assessment or setup remains unpriced, mark it unresolved. Do not add an item twice because it appears both in the vehicle offer and a separate allowance. The import and local comparison keeps these boundaries consistent across alternatives. A lower overseas listing amount is not the ready acquisition figure until its missing scope is resolved, and a port-arrival total is not automatically the customer’s usable purchase cost.
| Finding | Buying response |
|---|---|
| Inputs supported and scope consistent | Compare defined-period value |
| Important line unpriced | Retain it as unresolved |
| Decision depends on optimistic exit | Test a weaker scenario first |
Calculate energy from an explained input
Use annual distance, an appropriate consumption boundary and actual applicable tariffs. Where the available measurement is energy bought rather than a vehicle display, preserve that distinction. The energy-cost guide provides the narrower calculation. For illustration only, 20,000 kilometres a year at a hypothetical 18 kWh per 100 kilometres gives 3,600 kWh. At an invented USD 0.20 per kWh, that line is USD 720 yearly. Neither input is an E-QM5 rating or a tariff quotation. Replace them with supported figures, adding applicable access or parking charges where the scope requires them.
Use provider-supported recurring and occasional costs
Request the maintenance and relevant preparation inputs appropriate to the identified vehicle. Include insurance, tyres and other accepted cost categories with sources or explicit assumptions. A blanket annual service allowance can hide a known one-off item or double count work already in acquisition. The service planning record helps define tasks. For working vehicles, decide how downtime and backup capacity are treated, and avoid inventing lost revenue where the buyer has no defensible value. Keep a reserve distinguishable from a confirmed expense: unused contingency is not the same thing as a provider’s completed repair invoice.
Make the complete arithmetic transparent
A purely hypothetical USD worksheet could contain 14,000 acquisition, 2,160 three-year energy, 900 service, 1,500 insurance and 600 tyres. Before exit proceeds, those inputs total 19,160. Subtracting an assumed 8,000 exit amount produces 11,160 under that chosen scope. Every figure is an illustrative input, not an E-QM5 quote, forecast, premium or resale guarantee. Unknown categories remain open rather than zero. This example shows the arithmetic only. A buyer should be able to replace each line and see whether the decision changes instead of receiving a single attractive cost number with hidden assumptions.
Test the assumptions most likely to change the choice
Recalculate lower annual distance, less convenient charging, identified additional work or a lower exit assumption. In the same invented example, reducing exit from 8,000 to 6,000 adds 2,000 to the calculated period cost without changing energy consumption. Obtain credible local evidence before selecting any actual exit case. Use the battery condition decision for supported findings, not a speculative lifespan estimate. Scenario analysis does not predict which case will occur. Its purpose is to show whether the proposed purchase remains acceptable when the buyer cannot depend on the most favourable assumption.
Choose on supported usefulness as well as cost
Compare an acceptable alternative using the same period, distance and expense categories. Retain passenger suitability, charging access and receiving support alongside the worksheet; the cheapest calculated line is not useful if an essential task fails. New and used offers require their appropriate delivery and condition evidence. Preserve dated sources and revise the worksheet when a vehicle or proposal changes. The final decision should explain which assumptions matter and what uncertainty remains, without promising savings, future resale or an operating margin from an invented example that has not been replaced by the customer’s actual situation.
Keep the decision clear.
- One horizon and annual duty
- Ready acquisition scope
- Explained energy boundary
- Supported recurring costs
- Explicit exit and adverse scenarios
Before you decide.
Are the numbers in this example current E-QM5 prices?
No. They are invented worksheet inputs showing arithmetic and must be replaced with actual supported information.
Is the exit value guaranteed?
No. Treat it as an assumption and test a weaker case with relevant local evidence.